


Disponible en Español 
CEMLA Course: Financial Mathematics (practical)
September 28 - 30, 2026
CEMLA Mexico City, Mexico
Face-to-face format
From Theory to Application
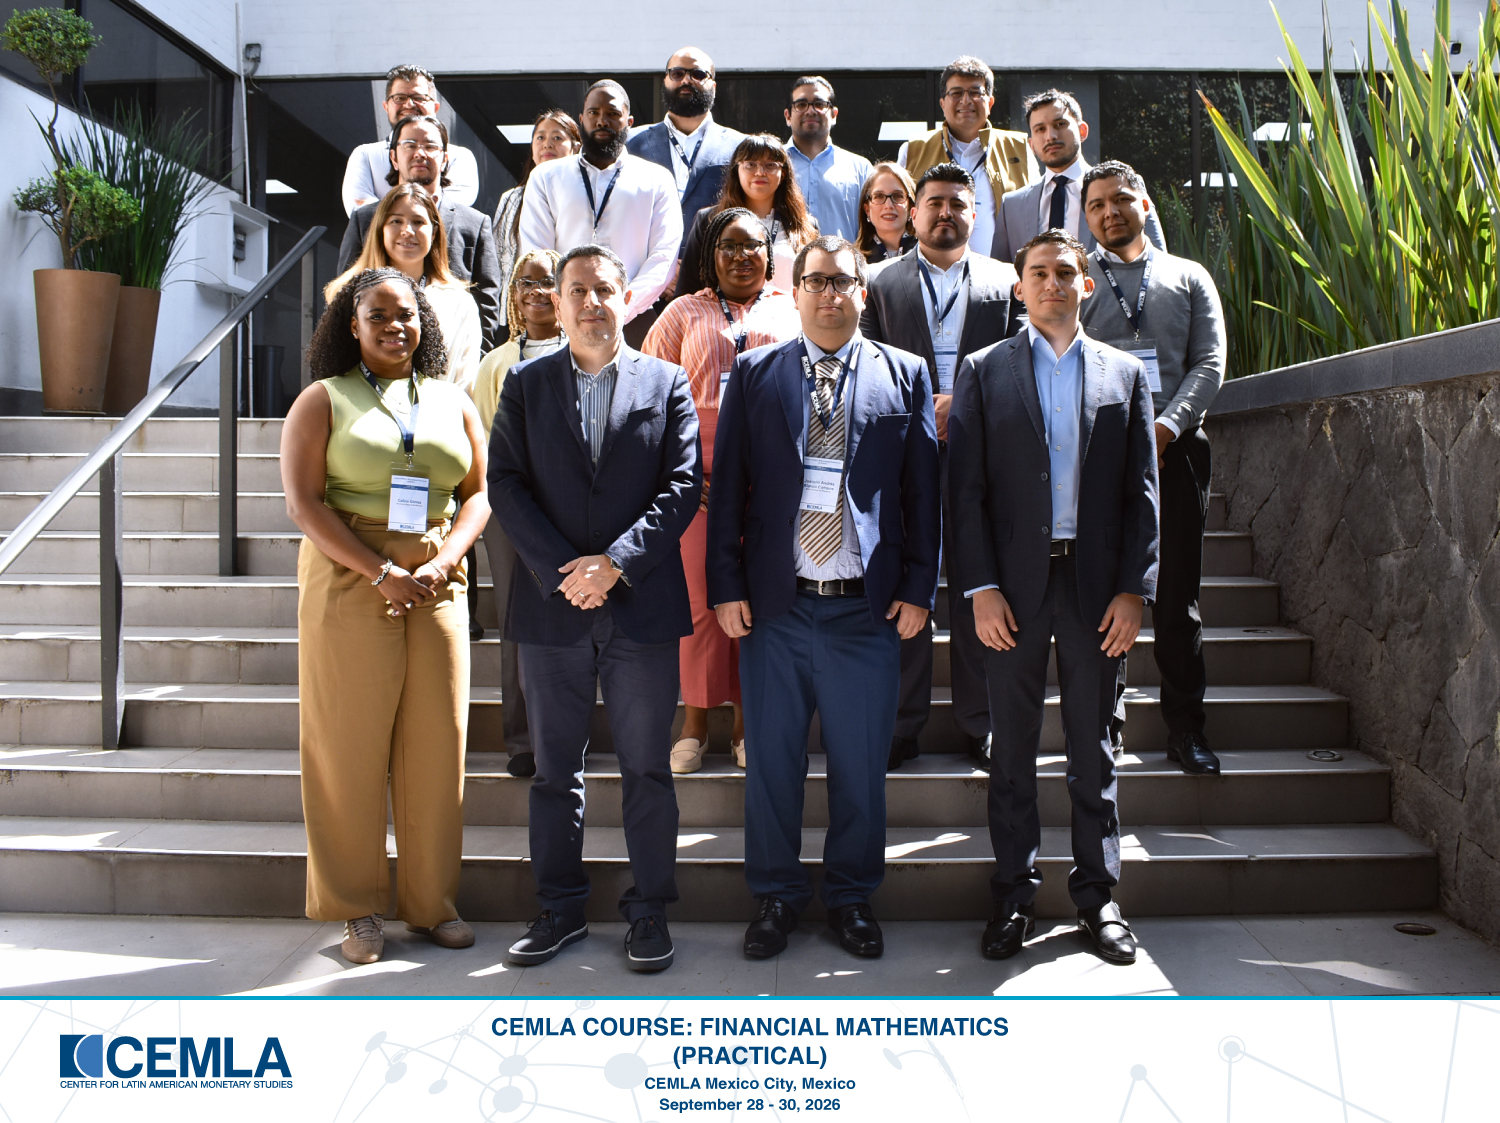
The practical component of the Financial Mathematics Course was held in person at CEMLA over three days. Its purpose was to revisit the ideas developed during the earlier virtual sessions and turn them into concrete valuation, optimization, and simulation procedures. The transition was deliberate: after studying the probabilistic and economic foundations of the models, participants were able to examine how those ideas are implemented, what information they require, and which decisions they can support.
The work combined explanations, short derivations, exercises, and case analysis. Numerical examples and market data were used throughout the sessions to maintain a clear connection between the theory and the problems faced by central banks, financial institutions, and risk management functions.
Option Valuation with the Binomial Model
The first day focused on derivatives valuation. It began with a one period binomial model to show transparently how a portfolio consisting of the underlying asset and a risk free position can replicate an option payoff. This construction produced the contract price through the absence of arbitrage and gave a concrete interpretation to the risk neutral measure: the objective was not to guess the actual probability of an upward or downward movement, but to identify the weights consistent with market prices and replicable cash flows.
The tree was then extended to several periods. Backward induction was used to value European options and, by comparing immediate exercise with continuation at each node, American options. The sessions also explained how the binomial model approaches the continuous Black Scholes framework as the number of periods increases. Participants could therefore see that the tree and the closed form formula are not separate approaches, but related representations of the same no arbitrage logic.
The day concluded with exercises based on actual market information. The discussion covered historical versus implied volatility, the sensitivity of valuations to model assumptions, and possible extensions, including situations in which trading itself can affect market prices. The emphasis was on interpreting a valuation rather than merely producing a number.
From Markowitz to Black Litterman
The second day concentrated on portfolio selection. The analysis began with the Markowitz mean variance model for risky assets. Through a series of examples, the optimization problem was formulated, constraints were introduced, and the method of Lagrange multipliers was used to obtain optimal portfolios and characterize the efficient frontier.
A risk free asset was then added. This extension led to the Capital Allocation Line, whose slope was interpreted as the Sharpe ratio, and to the identification of the tangency portfolio as the portfolio offering the highest expected compensation per unit of risk. This provided the connection with the CAPM: in equilibrium, the market portfolio occupies the tangency point, while the expected return of each asset depends on its contribution to systematic market risk, measured by beta.
The discussion concluded with the Black Litterman model, presented as a practical response to a well known limitation of Markowitz optimization: optimal weights can be highly sensitive to small changes in expected returns. By combining equilibrium returns with investor views, the model produces more stable estimates and more robust portfolios. The exercises illustrated how market information, expectations, and constraints can be brought together within a single decision framework.
Machine Learning and Integrated Applications
The third day broadened the discussion to machine learning tools. A simple neural network was first constructed so that participants could follow the complete flow of information: the input data, the transformations performed across layers, the resulting output, and the adjustment of parameters through an optimization algorithm. The purpose was to make these models less of a black box and to discuss not only when they can be useful, but also when their complexity or limited interpretability should discourage their use.
Reinforcement learning was then introduced through the Bellman equation. A Q learning example provided intuition about states, actions, and rewards when the value function can be represented by a matrix. A Double Deep Q Network was subsequently presented, replacing that matrix with a neural network approximation and thereby expanding the range of problems that can be addressed.
The final session brought several strands of the course together. It examined the difference between approximating a function and simulating a stochastic process, and compared option valuation through Monte Carlo simulation with the Black Scholes formula. This comparison helped clarify the assumptions underlying each method and encouraged participants to consider possible alternatives when those assumptions are not satisfied.
Overall Assessment of the Practical Component
The in-person component completed the connection between theory and application. The binomial model made replication and early exercise visible; portfolio optimization showed how risk preferences and market information can be translated into allocation decisions; and the machine learning and simulation sessions expanded the set of tools available for problems without a simple analytical solution.
The overall message was that a quantitative technique should not be judged solely by its sophistication. Its value depends on whether the problem is well formulated, the data are appropriate, the assumptions are explicit, and the results can be interpreted in financial terms. Practice therefore did not replace theory; it made it possible to understand what the theory is useful for, where it works, and where its limits lie.